Thinking about buying a rental near one of O’Fallon’s master-planned hubs? You’re not alone. Communities built around retail, parks, and trails can be magnetic for renters and future buyers. The key is knowing how amenities, HOA rules, and nearby supply shape your returns over time. In this guide, you’ll learn how to evaluate rentability, what to check in HOA documents, and how to underwrite both buy-and-hold and mid-term strategies in St. Charles County. Let’s dive in.
Why master-planned hubs attract renters
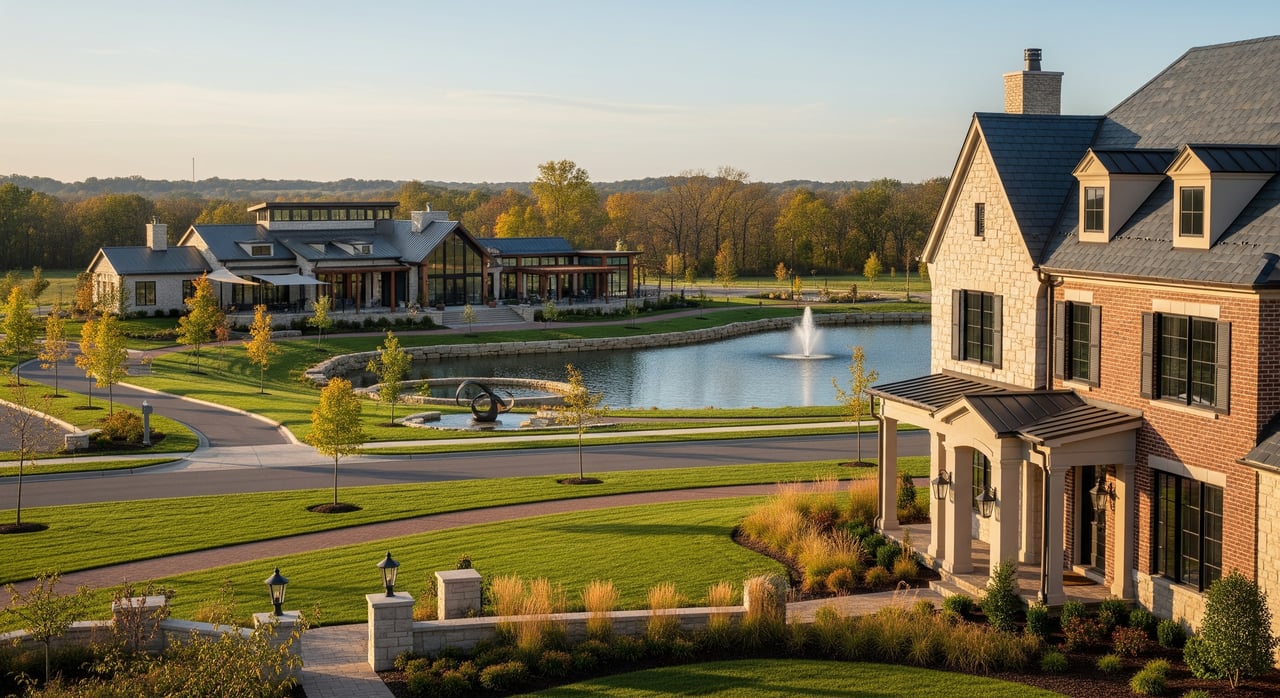
Master-planned areas often combine housing, trails, parks, and a retail core in one place. That blend creates daily convenience and a strong sense of place, which can support rental demand and resale premium. In St. Charles County suburbs like O’Fallon, proximity to employment centers and highway access adds another layer of appeal for commuters.
At the same time, every micro-area performs differently. Treat each subdivision and zip code as its own market. Pull local comps and verify commute times to nearby employers rather than relying on countywide averages. Retail near these hubs can help reduce time on market, but you should still evaluate tenant stability for anchors and essential services.
Product types and tenant demand
Single-family homes
If you want longer leases and lower turnover, single-family homes can fit well in suburban communities. Households that value space, garages, and private yards tend to stay longer, which can help smooth out vacancy. Proximity to parks, everyday retail, and schools can broaden the renter pool.
Townhomes and condos
Attached homes often deliver higher rent per square foot, plus walkable access to retail and services. These homes can appeal to commuters and smaller households who prioritize convenience and minimal maintenance. Expect potentially higher turnover than single-family homes and more sensitivity to HOA leasing policies.
Mixed-use or near retail cores
Homes adjacent to a strong retail lineup can command a convenience premium. Evaluate the tenant roster carefully. A stable grocery or service anchor is more durable than a lineup of novelty concepts. Also consider traffic, noise, and phasing. Early phases may experience construction disruption as the community builds out.
HOA and CC&R rules that shape returns
HOA rules can make or break a rental strategy. Before you write an offer, ask for the full HOA package: Declaration of Covenants, Conditions & Restrictions (CC&Rs), bylaws, rules and regulations, leasing addendums, architectural guidelines, meeting minutes, budget, reserve study, and any special assessment history. Also request the management company’s contact and insurance requirements.
Leasing caps and minimum lease terms
Some HOAs limit the percentage of homes that may be leased at one time. Others require minimum lease terms, such as 30, 90, or 365 days. If you plan to run a mid-term furnished rental, minimums matter. Confirm whether subletting is allowed and whether there are any owner-occupancy requirements before renting.
Approval, screening, and notices
Many HOAs require advance notice of a new lease, owner-sponsored tenant applications, or background checks. Build these steps into your leasing timeline to avoid fines. Ask for written policies and check meeting minutes for how strictly rules are enforced.
Parking, guests, and use restrictions
Guest rules and parking allocations can affect appeal for multi-vehicle or group renters. Review business-use and occupancy language carefully if you plan mid-term housing for traveling professionals.
Assessments, reserves, and maintenance
HOA dues are a recurring expense that affects net cash flow. Review the latest budget and reserve study to gauge the likelihood of special assessments. Clarify who maintains exteriors, landscaping, and common areas, and confirm required owner insurance coverage.
Underwriting buy-and-hold vs mid-term rentals
Start with a clean framework and use local comps for every input.
Metrics to run on every deal
- Gross Rent Multiplier (GRM) = Purchase Price / Annual Gross Rent
- Net Operating Income (NOI) = Gross Rent − Operating Expenses
- Capitalization Rate = NOI / Purchase Price
- Cash-on-Cash Return = Annual Cash Flow / Cash Invested
Use conservative vacancy and turnover assumptions that match the property type. Single-family rentals often have lower turnover than attached homes. Mid-term furnished rentals can deliver higher gross rent but bring more operating costs and management time.
Inputs to verify locally
- Market rents: Pull recent leased comps within 1 and 3 miles for the same product type and finish level.
- Property taxes: Obtain the precise tax rate from the county assessor and confirm the current tax bill.
- Insurance: Check any HOA-driven insurance requirements and price appropriate coverage.
- HOA dues: Include monthly dues in your pro forma and note any pending special assessments.
- Management and turnover costs: Expect higher costs for mid-term furnished rentals due to utilities, cleanings, and marketing.
Financing checks
Investment loans usually require higher down payments and carry higher rates. Lenders often review HOA health for condos and townhomes, including reserve balances and owner-occupancy ratios. Confirm project eligibility early, especially in larger multi-phase developments.
Risks to watch and how to mitigate them
Oversupply and phasing
In master-planned areas, new phases can add supply. Monitor city and county permits and planning agendas. If large for-sale or rental phases are in the pipeline, adjust your rent growth and time-on-market assumptions.
Mitigation: Favor product with durable local demand, such as 3-bedroom single-family homes, and underwrite conservative rent growth.
Retail hub stability
Retail churn or the loss of anchors can reduce the appeal of a nearby neighborhood. Evaluate the tenant mix and vacancy of the retail core. Consider how traffic patterns and parking changes could affect livability.
Mitigation: Prioritize locations near stable service anchors and balanced tenant mixes. Underwrite a downside scenario with slower lease-up and modest rent growth.
Policy and legal layers
Municipal short-term rental rules and licensing can apply regardless of HOA policy. Zoning, rental registration, and inspections may also be required.
Mitigation: Verify city and county rules early and confirm that HOA enforcement aligns with local ordinances. If the CC&Rs include unusual leasing restrictions, consult a local real estate attorney.
School boundaries and demand
Boundary changes and ratings can influence household choices over time. Keep references neutral and focus on proximity and access.
Mitigation: Validate school boundary maps directly with official sources and avoid assumptions in your underwriting.
Special assessments and HOA litigation
Unexpected assessments can disrupt cash flow. Litigation can complicate financing and resale.
Mitigation: Review the reserve study, recent assessment history, and meeting minutes. Ask the HOA for any pending litigation disclosures.
Step-by-step due diligence checklist
Use this checklist for any property near a master-planned hub, including areas around retail destinations like the Streets of Caledonia. Confirm specifics directly with official sources and HOA management.
- Market and comps
- Pull 12 to 24 months of sales and rental comps within 1 and 3 miles.
- Track days on market, list-to-sale ratios, and recent rent trends by unit type.
- HOA and legal
- Obtain CC&Rs, bylaws, rules, last 12 months of minutes, budget, reserve study, insurance certificate, and special assessment history.
- Confirm leasing caps, minimum lease terms, approval process, parking and guest rules, and any owner-occupancy requirements.
- Municipal and regulatory
- Check with the City of O’Fallon and St. Charles County for rental registration, short-term rental rules, inspections, and licensing.
- Confirm current zoning and any pending rezoning or nearby development applications.
- Physical and financial
- Order an independent home inspection and get contractor estimates for near-term repairs.
- Verify utility responsibilities and HOA maintenance obligations.
- Confirm parcel ID, current tax bill, and check for any liens or delinquent taxes.
- People and process
- Speak with the HOA manager and, if possible, a few current owners about enforcement.
- Interview at least two local property managers to validate realistic rents, vacancy, and turnover for the exact product type.
Scenario planning for O’Fallon investments
- Best case
- Stable retail anchors, limited new supply, and consistent demand for nearby housing. Result: stronger rent growth, shorter vacancies, and a resale premium tied to convenience and community branding.
- Base case
- Rent growth near inflation, routine HOA dues, and limited assessments. Result: predictable cash flow and moderate appreciation.
- Downside
- Retail churn or a large new competing community, plus tighter HOA rental caps or a special assessment. Result: higher vacancy, slower rent growth, and softer resale.
Local sources worth contacting
- St. Charles County Assessor for parcel data and property tax details.
- City of O’Fallon Planning & Development for permits, zoning, and development plans.
- St. Charles County Recorder of Deeds for recorded CC&Rs and plats.
- U.S. Census Bureau (ACS) for household and demographic context.
- Bureau of Labor Statistics and Federal Reserve (FRED) for employment and economic indicators.
- St. Louis Association of REALTORS or Missouri REALTORS and your local MLS for current sales and rental comps.
- Experienced local property managers, mortgage brokers familiar with investor loans, and a real estate attorney versed in Missouri HOA and landlord-tenant law.
How we can help you move forward
If you’re weighing an investment near an O’Fallon master-planned community, a clear plan makes all the difference. We’ll help you gather the right comps, coordinate HOA document requests, and introduce you to trusted local vendors for property management, inspections, and legal review. Our concierge approach keeps your process organized and your underwriting grounded in local facts.
Ready to run the numbers and see if a property pencils? Request a complimentary home consultation and a personalized plan with The Monschein Team.
FAQs
Can I rent out a home near an O’Fallon master-planned hub?
- Review the HOA’s CC&Rs for leasing caps, minimum lease terms, and approval steps, and verify any city or county rental registration or inspection requirements.
Are mid-term rentals allowed in HOA communities in St. Charles County?
- Many HOAs restrict short-term rentals and set minimum lease lengths; confirm written rules and municipal ordinances before pursuing a 30 to 90-day strategy.
Which property type is best for a long-term rental near these communities?
- Single-family homes often deliver longer leases and lower turnover, while townhomes and condos can yield higher rent per square foot but may see higher churn; validate with local comps.
Will being next to a retail core help my resale value?
- A stable, well-leased retail hub with essential anchors can support demand and reduce time on market, but assess tenant stability, phasing, traffic, and noise.
How do HOA dues and special assessments affect returns?
- Treat monthly dues as an ongoing operating expense and review reserve studies and assessment history to gauge downside risk and protect your cash flow.